
CondoScan Condo Insurance Guide
Your building's master policy protects the structure, not your unit, your belongings, or your liability. Those are yours to insure. Here's what to ask your broker for, and how to get set up.
Download this guideFour things your insurance policy should have
- Contents Insurance
- Deductible Coverage
- Betterments and Improvements Coverage
- Additional Living Expenses
1. Contents Insurance
A burst pipe ruins your furniture, or a guest slips and injures themselves in your unit. The master policy stops at the building itself. Everything inside the unit is on you.
What it covers
- Contents: your belongings (furniture, electronics, clothing, valuables) if they're damaged or stolen.
- Personal liability: legal costs and damages if someone is injured in your unit or you accidentally damage someone else's property.
2. Deductible Coverage
Your washing machine leaks into the unit below, causing $28,000 in damage. The master policy pays, but its deductible is often passed on to you. With a $25,000 deductible, you owe $25,000.
What it covers
- Coverage for the corporation's deductible. The exact amount is on the insurance certificate in your CondoScan insurance package, and it's also stated in your report.
- Room to grow. After a claim, corporations often raise their deductible, sometimes to $50,000. If your coverage only matches today's number, a future increase leaves you with a gap.
3. Betterments and Improvements Coverage
You renovated your kitchen: custom cabinetry, quartz countertops, hardwood floors. After a fire, the master policy only restores the original standard finishes, not your upgrades.
What it covers
- Everything above the Standard Insurable Unit Description (SIUD), the corporation's list of original finishes. The SIUD may say vinyl countertops even if your kitchen is quartz; the difference is yours to insure.
- The insurance certificate in your CondoScan package will say whether the corporation covers betterments. If it does, ask the seller whether they registered their improvements, or contact management for next steps.
4. Additional Living Expenses
A fire leaves your unit uninhabitable for months. You need somewhere to live, storage for your belongings, and meals while your kitchen is out of commission.
What it covers
- Temporary housing: a comparable rental while yours is repaired, including hotels, furnished apartments, or short-term rentals.
- Extra day-to-day costs: the gap between your normal living costs and the cost of being displaced: meals, storage, laundry. Not a blank cheque, but meaningful protection.
How to read your insurance certificate
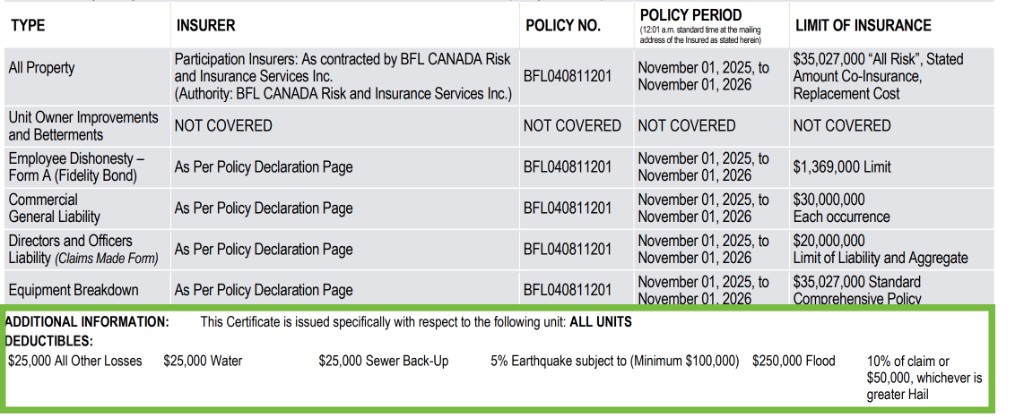
Your CondoScan insurance package includes the corporation's certificate. Two lines on it matter most for your personal policy: deductibles, and unit owner improvements and betterments.
1. Deductibles
Look for the DEDUCTIBLES line near the bottom of the certificate. On this sample, water, sewer backup, and all other losses are each $25,000. That is the amount to put on your own policy. Cover the highest number listed, and keep a maximum of at least $50,000 in case the corporation raises it after a claim.
2. Unit owner improvements and betterments
Look for the row labelled Unit Owner Improvements and Betterments. If it says NOT COVERED, you insure upgrades yourself. If the corporation does cover them, ask the seller whether they registered their improvements, or contact management for next steps.
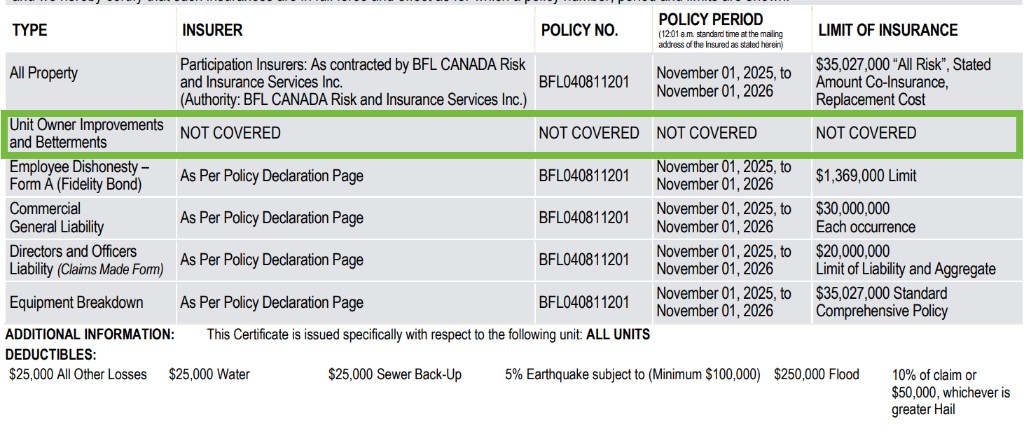
This is a sample certificate. Yours will look similar; the amounts and whether betterments are covered will differ.
What to do next
Getting set up
Once you know what to look for, here's how to get it onto your policy.
- Download your insurance package from CondoScan. In the platform, go to Files → Download Insurance Package. The certificate inside has everything your broker needs, including the master policy deductible.
- Give the certificate to your insurance broker. Ask them to match your deductible coverage to the amount listed, with a maximum of at least $50,000.
- Confirm all four coverages are on your policy. Before you sign off, walk through the list at the top of this guide with your broker.
Alberta-focused. Not insurance advice. Consult a licensed broker for your situation.
Know what your condo corporation actually covers
CondoScan reviews your condo documents and flags gaps, so you know what to tell your insurance broker.
Start your review